When a lender evaluates financing for a rural business, the borrower’s projections often need independent support. A rural business feasibility study provides that support by testing whether a proposed project can succeed and repay the debt. It is a type of feasibility study report built around the unique conditions of rural markets. Below, we outline the key elements of a rural business feasibility study and what each one tells a lender.
As a trusted valuation firm, Peak Business Valuation prepares feasibility studies for lenders and borrowers across the country. We can produce independent studies that meet USDA expectations and support sound underwriting. If you have questions about a rural business feasibility study, we are happy to help. Schedule a free consultation below to get started.
Why a Rural Business Feasibility Study Matters
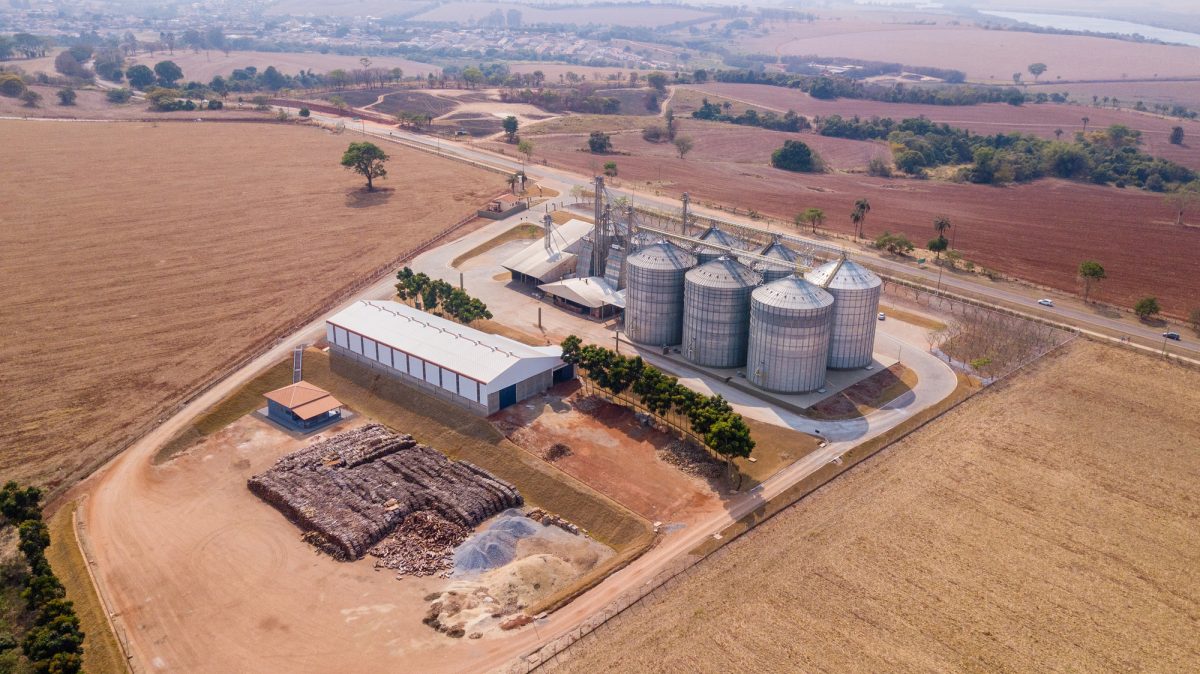
Rural markets behave differently from urban and suburban markets. Demand is often thinner and more dispersed, which makes revenue harder to project. Many rural economies also depend on a single industry or a seasonal cycle, so a downturn can affect the whole area at once. In addition, rural projects frequently involve special-purpose properties. These facilities carry greater lending risk because they may have few alternative uses, which limits a lender’s ability to recover value if the project fails.
A rural business feasibility study helps a lender analyze these risks with objective insight. It tests the borrower’s assumptions against real market and financial data. This is especially valuable when there are few comparable businesses in the area. For a USDA Business and Industry (B&I) guaranteed loan, an independent study is often required as part of the application process. In each case, the study gives the lender a clearer understanding of whether a project can meet expectations and repay the loan.
Key Components of a Rural Business Feasibility Study
A complete rural business feasibility study examines the project from several angles. Each component addresses a distinct type of risk that a lender needs to understand before approving funding. Below, we outline the six areas an analyst typically evaluates during a USDA-approved feasibility study.
Market Feasibility
The market feasibility analysis asks whether enough demand exists to support the project. As part of a market feasibility study, an analyst reviews the customer base, market size, competition, and local demand trends. In rural areas, this analysis carries extra weight because a small or dispersed population can limit revenue. The findings tell a lender whether the projected sales are realistic for the market the business will serve.
Financial Feasibility
The financial component of a rural business feasibility study tests whether the project can generate enough cash flow to sustain operations and meet debt obligations. An analyst reviews cost estimates, revenue projections, cash flow forecasts, and the break-even point. Lenders tend to review this section most closely, since it directly impacts repayment capacity. This analysis helps a lender determine the appropriate loan amount and confirm that debt service coverage holds up.
Operational Feasibility
Operational feasibility considers whether the business can run day-to-day with the resources available. The analyst reviews staffing, workflow, suppliers, and the owner’s capacity to manage operations. Rural businesses often face challenges in this area due to factors such as a limited local labor pool or fewer nearby suppliers. Understanding these factors helps a lender judge whether the plan is realistic in practice.
Technical Feasibility
A rural business feasibility study also includes a technical analysis of the site, equipment, and facilities the project requires. The analyst considers whether the necessary infrastructure, such as utilities and transportation access, is available at the location. This matters in rural settings where limited infrastructure can raise costs or delay a project. As such, the analysis helps a lender identify technical obstacles before they affect the timeline or the budget.
Management Feasibility
Management feasibility evaluates whether ownership and management can run the business effectively. The analyst reviews the management team’s experience, depth, and history of running a similar operation. Strong management gives a lender more confidence that the team can execute the plan. If experience and skills are limited, the study can help determine where additional support or hiring is needed.
Legal and Regulatory Feasibility
Finally, the legal and regulatory component of a rural business feasibility study confirms that the venture can operate within the rules that apply to it. This includes licensing, permits, zoning, and any industry-specific regulations. For projects such as food processing, childcare, or healthcare, these requirements can affect startup timelines and costs. Identifying them early helps a lender avoid surprises that could stall the project after funding.
These six components give a lender a complete view of a project’s viability and risk. To ensure a credible feasibility study, it is important to work with a provider who is familiar with rural markets. Peak Business Valuation frequently prepares studies that meet USDA and lender requirements. Schedule a free consultation below to learn more.
How to Use a Rural Business Feasibility Study
For a lender, a market feasibility study is a useful tool for underwriting, structuring, and ongoing credit monitoring. Below, we outline how lenders can put the findings of the study to work.
First, the study helps a lender validate the borrower’s projections. Rather than relying on the borrower’s estimates alone, the lender can refer to an independent analysis when building the credit memo. This is where a feasibility study differs from the borrower’s business plan, which reflects the owner’s personal assumptions for the project.
Next, the feasibility study report guides how the lender structures the loan. Financial projections and risk factors help determine the loan amount, terms, and any conditions the lender may attach before closing. For USDA-backed loans, the study also helps support the agency’s review.
Moreover, an independent study is useful after closing. Lenders can return to the market data, financial projections, and risk assessment to monitor performance and revisit assumptions over the life of the loan.
Conclusion
A rural business feasibility study gives a lender objective insight into whether a project can succeed and repay the loan. By examining market, financial, operational, technical, management, and legal feasibility, the study addresses the unique risks that come with rural lending decisions. Understanding each element helps a lender make informed decisions and evaluate the loan opportunity more effectively.
Peak Business Valuation can provide rural business feasibility studies for lenders and borrowers. We take careful measures to ensure our reports meet USDA and lender standards and support informed credit decisions. Schedule your free consultation with Peak Business Valuation below to get started.